
Register for our upcoming Public Development Community of Practice (PDCOP) event on Thursday, October 29, from 11:30 AM to 12:30 PM ET, which focuses on credit enhancement of municipal bonds for housing. Credit enhancement is a financial strategy that housing authorities, cities, counties, and states can use to secure better borrowing terms for housing by reducing risk for bond investors. Center for Public Enterprise (CPE) will open the session with an introduction to the topic: what credit enhancement is and the forms it can take. We’ll then hear from two experts on the subject: Sam Adams of KeyBanc Capital Markets and Patty Huddle of the Columbus-Franklin County Finance Authority (CFFA). This post previews the topics we’ll cover during the event, with the full agenda and information about the speakers at the end.
Register on Zoom
Why credit enhancement, and why now?
State and local governments want more affordable and workforce housing, but funding is scarce and interest rates remain elevated. As financing through the Low-Income Housing Tax Credit (LIHTC) becomes more competitive and reliant on state and local governments to fill the gap, many are looking to tools like mixed-income revolving loan funds and funded inclusionary zoning programs, such as property tax incentives, to produce affordable housing units in otherwise market-rate developments. In some jurisdictions, local governments and housing authorities look to take matters into their own hands by issuing tax-exempt bonds and use legally pledged revenues or other credit support to secure better credit ratings and financing.
Municipal bonds are debts that states, cities, counties, and other public entities (like housing authorities) issue to pay for long-term capital projects like infrastructure, schools, and housing. A credit rating refers to how third-party rating agencies such as Standard & Poor’s (S&P), Moody’s, or Fitch assess the creditworthiness of an issuer or a specific bond, including the likelihood of timely repayment. An “investment grade” rating includes those rated BBB- through AAA.1
Credit enhancement is when a stronger financial party (a government, guarantor, or insurer with an investment grade rating) backs a bond or loan that would otherwise not be able to achieve as high a rating due to its ordinary risk profile. This pledge of external credit lowers the risk to investors in the bond/loan, which can mean lower interest rates or better terms for borrowers, whether or not the financing receives a higher formal credit rating. Private entities can also provide credit enhancement in the form of mortgage insurance, bond insurance, bank letters of credit, or guarantees. Tools like credit enhancement may be more important now in an elevated interest rate environment. State and local governments can deploy them creatively to collaborate in the production and preservation of affordable housing. And while our upcoming session focuses on housing, credit enhancement and guarantees have wide-ranging applicability to public infrastructure and social goals. For example, Texas’ Permanent School Fund, supported in part by royalties paid by the oil and gas industry, provides a guarantee program that backs over $129 billion in bonds issued by over 900 school districts for school facility construction and building upgrades, ensuring that participating districts can all issue investment-grade credits.2
Approaches to strengthening housing bond financing
Credit enhancement of municipal bonds comes in a few different forms, most of which provide a backstop for debt service if a borrower is unable to make timely payments. The structures differ in whether that backstop is legally binding, what is being pledged (e.g., a government’s taxing power, general revenues, or a reserve fund), and whether bond issuers pool their credit with others. The following section provides examples of four approaches to strengthening housing bond financing including: full faith and credit pledges, moral obligation pledges, general revenue pledges, and pooled bond funds. These approaches are often combined.
- Full faith and credit pledges. A full faith and credit pledge is a government’s guarantee that it will use its taxing authority and revenues to make its debt payments, the same backing behind its general obligation bonds. A government can also extend this pledge to back another borrower’s debt. For example, in the Seattle metro area, King County offered its full faith and credit as a loan guarantee to enhance the creditworthiness of the King County Housing Authority (KCHA).3 This credit enhancement program was structured through contingent loan agreements, which means that the County agreed to lend its own funds only if the borrower couldn’t make debt service payments on time.
King County authorized a credit enhancement program for housing in 1997 and established a $50 million project-based credit enhancement program in 1998. This program was available to nonprofit, and for-profit developers building housing for households at or below 80% of area median income (AMI). The County reviewed each project individually on a rolling basis, and the program grew to $200 million by 2008. Because KCHA was the primary user of the program during this time, the County amended its code in 2017 to create a new $200 million credit enhancement program exclusively for KCHA, alongside the existing program. The exclusive partnership between the County and KCHA was based on KCHA’s overall financial strength rather than reviewing each proposed project. This gave the housing authority readier access to the municipal bond market and allowed it to move more quickly on its acquisitions. In 2018, S&P rated $90 million of KCHA bonds AAA based on the County’s credit enhancement while bonds KCHA sold at the same time without credit enhancement were rated AA.4 KCHA could request new commitments from the County through 2022 with existing guarantees on bonds to remain in place until those bonds are repaid. - Moral obligation pledges. A moral obligation pledge is a government’s promise to request funds from its legislature or council to cover a borrower’s debt payments if the borrower falls short. A moral obligation often “requires the issuer to maintain a debt service reserve fund at a specified reserve requirement, typically the maximum annual debt service, and report any deficiencies that arise to an appropriate official of state or local government,” according to the Council of Development Finance Agencies (CDFA). Unlike a full faith and credit pledge, moral obligations aren’t legally enforceable, and are subject to appropriation, so rating agencies usually treat them as weaker support. However, a government that fails to honor a moral obligation can expect its own credit rating to suffer which would limit its long-term lending and borrowing for other projects.
A cautionary tale of this is New York State’s Urban Development Corporation (UDC) which used moral obligation bonds heavily in the late 1960s and 70s initially to finance low-to moderate-income housing projects and large-scale mixed-income communities. When the UDC defaulted on $104.5 million in bonds in 1975, New York State stepped in with an infusion of cash to save its projects still under construction and bring them to completion.5 While broader macroeconomic challenges persisted in the mid-1970s, the UDC default raised doubts on moral obligation bond issuances throughout the country with a 1975 Time Magazine article stating that following the default “[UDC] bond prices fell rapidly; some bonds sold for half their face value, and by week’s end most other outstanding issues had fallen by more than $100 per $1,000 bond.” Despite this era of challenges, moral obligations and similar structures continue to be used and often include additional safeguards, backstops, and guarantees to prevent these defaults from occurring again.
In Alexandria, VA, the City pledged to cover the estimated $3.5 million in annual debt service payments if the Alexandria Redevelopment and Housing Authority (ARHA) couldn’t make its payments on a $56.8 million purchase of a 133-unit senior housing building.6 The purchase was financed in 2025 through the Virginia Resources Authority (VRA) Virginia Pooled Financing Program, which sells bonds using its competitive AAA/AA credit rating and then lends the proceeds to local governments. VRA opened the program to affordable and workforce housing in 2023, and ARHA’s acquisition was the first housing project financed. VRA requires a local guarantee or moral obligation pledge from a county, city, or town in addition to meeting its underwriting criteria.7 As an additional backstop, VRA includes a “state intercept” feature whereby the state could withhold payments to the City up to the full amount owed to VRA. In the ARHA acquisition, the City negotiated additional safeguards including limiting ARHA’s ability to undertake other projects until the acquisition was complete and the property was successfully operating for 12 months as well as a pledge of revenues and real properties valued at $6 million as collateral.89 - General revenue pledges. A credit-rated public housing authority (PHA) can issue bonds backed by a pledge of its general revenues to acquire, construct, or preserve workforce and affordable housing. A general revenue pledge means the housing authority guarantees project debt service shortfalls to be paid from its non-restricted revenue streams. This can provide a substantial credit enhancement to bond issuances, according to Sam Adams, Managing Director, Affordable Housing and Public Housing Authorities at KeyBanc Capital Markets in an interview with Tax Credit Advisor.
One example is the Columbus Metropolitan Housing Authority (CMHA) which earned an A+ credit rating from S&P and partnered with The NRP Group, a private developer, on a new construction four percent LIHTC project called Sinclair Apartments. CMHA’s credit enhancement through the issuance of tax-exempt and taxable bonds backed by a general revenue pledge meant that the project was able to receive an interest rate about 100 basis points (1 percentage point) below other market financing at the time.10 - Pooled bond funds. A pooled bond fund combines public and sometimes private credit support into a single investment-grade structure, letting borrowers that couldn’t get a rating on their own sell bonds to national investors. (VRA’s program, described above, is a statewide example.) The Central Ohio Regional Bond Fund (CORBF) is a regional example administered by the Columbus-Franklin County Finance Authority (CFFA), a port authority under Ohio law. CFFA was created in 2006 and CORBF closed on its first financing in 2007 with an initial $10 million in reserves funded by the City of Columbus and Franklin County along with a letter of credit from Huntington Bank.11
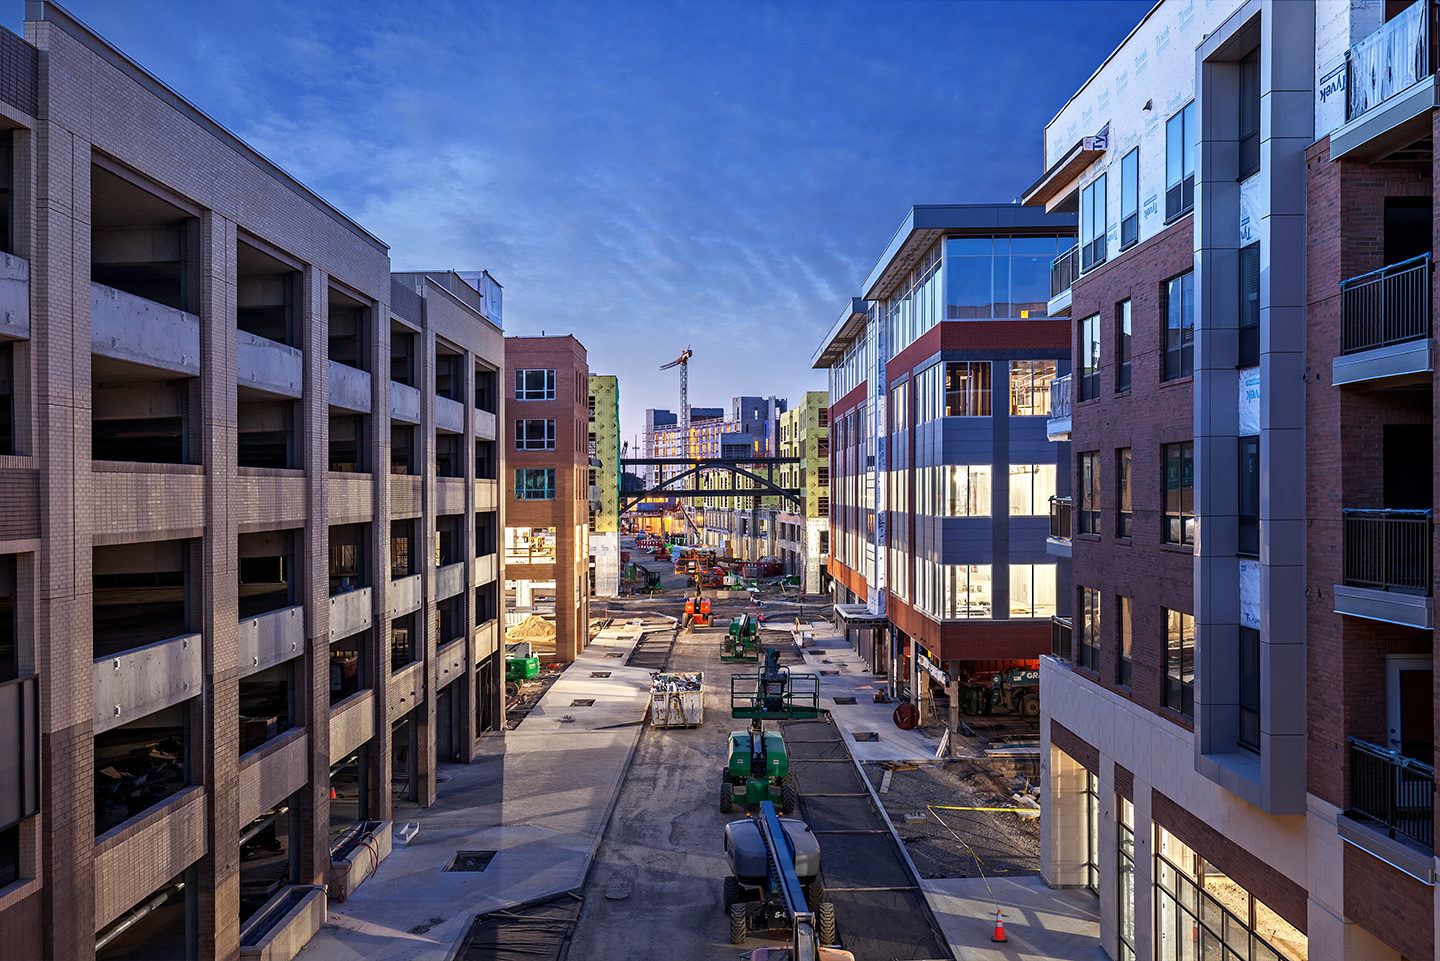
CORBF borrowers pledge a revenue stream backed by obligations such as payments in lieu of taxes (PILOTs), Tax Increment Financing (TIF), or corporate revenues to repay loans to CFFA. CFFA issues bonds supported by those sources of repayment, the fund’s reserves, and other credit support. These protections help cover borrower shortfalls, and the credit assessment considers the funds portfolio as well as the shared support. The CORBF has an A rating from S&P12 which gives projects long-term, fixed-rate financing and access to national investors they couldn’t reach on their own. Projects supported by the CORBF include Bridge Park, which is a redevelopment of 30 acres of underutilized land in Dublin, OH into a walkable mixed-use neighborhood that includes office, retail, and restaurant space, 700+ rental apartments and 200+ for-sale condos and townhomes13, in addition to public roads, parking garages, and other public infrastructure improvements.14
Conclusion
These examples show a range of how state, local, and housing authorities facilitated credit enhancement programs to finance housing developments and acquisitions. If you are a public sector professional evaluating a program, or want to understand more about one of these specific examples, you can bring your questions to our guest speakers on October 29.
This article is intended to provide accurate information gathered from a variety of publicly available sources about the subject matter covered. The author and Center for Public Enterprise are not providing legal or financial advice nor offering other professional services. Those seeking to engage further on these topics are encouraged to conduct thorough research and consult with qualified professionals before making any investment decisions.
About the Public Development Community of Practice (PDCOP)
The Public Development Community of Practice (PDCOP) is a working group for public sector employees including public housing authorities, housing finance agencies, and other state and local housing agencies to develop best practices for public development as a method of growing affordable multifamily housing production. PDCOP aims to meet quarterly with virtual presentations from practitioners around the country who are implementing innovative models to deliver new housing production including tax credit-free affordable housing units as a supplement to federally supported production.
Interested in joining? CPE welcomes public sector employees to request to join by filling out this form.
Register for Upcoming Event
Public Development Community of Practice: Credit Enhancement of Municipal Bonds for Housing
Thursday, October 29, 2026, 11:30 AM to 12:30 PM ET
Register for event on Zoom
Agenda
- Introduction and National Updates – 11:30 – 11:45 am
- Ashwin Warrior, Director of Housing, CPE
- Liz Sidor, Housing Program Manager, CPE
- Presentations – 11:45 am- 12:15 pm
- Sam Adams, Managing Director, Affordable Housing and Public Housing Authorities, KeyBanc Capital Markets
- How Public Housing Authorities can establish and/or improve their credit ratings.
- How PHAs, nonprofits, or developers might partner with cities, counties, or other municipal bond issuers to utilize credit ratings for superior debt.
- Case Study: King County and the King County Housing Authority Credit Enhancement Program (Seattle, WA metro area).
- Patty Huddle, President, Columbus-Franklin County Finance Authority (CFFA)
- Origins of the Central Ohio Regional Bond Fund.
- How CFFA raised the initial capital for the fund.
- Case Study: Bridge Park mixed-use development including condos and apartments.
- Sam Adams, Managing Director, Affordable Housing and Public Housing Authorities, KeyBanc Capital Markets
- Q&A with Presenters – 12:15 – 12:30 pm
Meet the Presenters
Sam Adams – Managing Director, Affordable Housing and Public Housing Authorities, KeyBanc Capital Markets
KeyBanc Capital Markets has worked with Public Housing Authorities (PHAs) to secure credit ratings by Standard and Poor’s (S&P) which helps PHAs to issue municipal bonds like other governmental entities by pledging general revenues. This can secure debt at better rates and terms due to the organizational credit enhancement of an investment grade government entity. PHAs, large or small, can partner with cities and counties to further strengthen bond offerings. The general revenue pledge means that the PHA is willing to make up for any project debt service shortfalls from their non-restricted revenue streams. This structure can be used to acquire or rehab additional properties for their portfolio or to partner with an affordable housing developer on 4% low-income housing tax credit projects. Credit enhancement is a powerful tool in particular for larger housing authorities operating in metro areas in need of affordable housing where states are capped out on how many tax-exempt private activity bonds (PABs) they can issue.
Patty Huddle – President, Columbus-Franklin County Finance Authority (CFFA)
CFFA is a port authority that provides financing solutions for economic development projects in Central Ohio, and has provided over $4.5 billion in financing to public improvement, mixed-use commercial/housing developments, and energy efficiency improvement projects since its creation in 2006. CFFA manages the Central Ohio Regional Bond Fund (CORBF) which has an A rating from S&P and provides a credit enhancement to public improvement projects by providing capital into the project through the issuance of a bond that is repaid through obligations such as payments in lieu of taxes (PILOTs) or Tax Increment Financing (TIF) that a project has secured. The bond is rated on the performance of the CORBF portfolio rather than the borrower’s credit. The CORBF is an investment-grade vehicle that offers qualifying developments the opportunity to leverage additional debt or achieve better loan terms by providing access to national capital markets that would have otherwise been unavailable to the project.
Header Photo Credit: Columbus Franklin County Finance Authority, Bridge Park
Footnotes
- 2020. Credit Rating Basics for Municipal Bonds on EMMA®. Municipal Securities Rulemaking Board. https://www.msrb.org/sites/default/files/Credit-Rating-Basics-for-Municipal-Bond-Investors.pdf
↩︎ - “Bond Guarantee Program.” Texas Permanent School Fund Corporation. ↩︎
- 2017. Staff Report: Proposed Ordinance 2017-0376 — King County Housing Authority Credit Enhancement Program. Metropolitan King County Council, Health, Housing and Human Services Committee. Accessed Online: https://mkcclegisearch.kingcounty.gov/LegislationDetail.aspx
↩︎ - 2019. Meeting of the Board of Commissioners, September 16, 2019. King County Housing Authority, pg. 21 https://www.kcha.org/Portals/0/PDF/Board/201909%20KCHA%20BOARD%20PACKET.pdf
↩︎ - Freemark, Y. 2011. “Roosevelt Island: Exception to a City in Crisis.” Journal of Urban History 37(3): 355–383, p. 371.
↩︎ - 2025. “PRESS RELEASE: ARHA PURCHASES THE ALATE SENIOR LIVING FACILITY FOR LADREY RESIDENTS.” Alexandria Redevelopment and Housing Authority (ARHA). https://www.arha.us/press-release-arha-purchases-alate-senior-living-facility-ladrey-residents
↩︎ - 2023. Affordable and Workforce Housing Criteria. Virginia Resources Authority. https://virginiaresources.gov/wp-content/uploads/2024/03/Affordable-and-Workforce-Housing-Underwriting-Criteria_adopted-as-of_2023_12_12_.pdf
↩︎ - 2025. Resolution Approving The Execution And Delivery Of A Support Agreement And Performance Agreement For Alexandria Redevelopment and Housing Authority.
https://alexandria.legistar.com/View.ashx?M=F&ID=14306698&GUID=DFBE142E-A5AC-4BCC-A5DB-787946C3E964
↩︎ - 2025. Performance Agreement Between the City of Alexandria, Virginia and Alexandria Redevelopment and Housing Authority. City of Alexandria, Virginia.
https://alexandria.legistar.com/View.ashx? ↩︎ - Fogarty, M.. 2024. “Case Study: Using General Revenue Bonds to Support Workforce Housing.” Tax Credit Advisor. https://www.taxcreditadvisor.com/articles/case-study-using-general-revenue-bonds-to-support-workforce-housing/ ↩︎
- 2026. “The Central Ohio Regional Bond Fund: What It Is, How It Started.” Columbus-Franklin County Finance Authority.
https://columbusfinance.org/news/the-central-ohio-regional-bond-fund-what-it-is-how-it-started/
↩︎ - Research Update: Columbus-Franklin County Finance Authority, OH Development Revenue Bond Rating Raised To ‘A’ On Increasing Reserves https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3594245 ↩︎
- Crawford Hoying, project developer’s webpage. https://www.crawfordhoying.com/projects/bridge-park
↩︎ - Columbus-Franklin County Finance Authority webpage. https://columbusfinance.org/projects/bridge-park/ ↩︎